Fixed or variable is the question every mortgage shopper asks first — and it's the question most often answered with a generality instead of your actual situation. The honest answer: the right choice depends on you, not the rate cycle.
What a fixed rate gives you
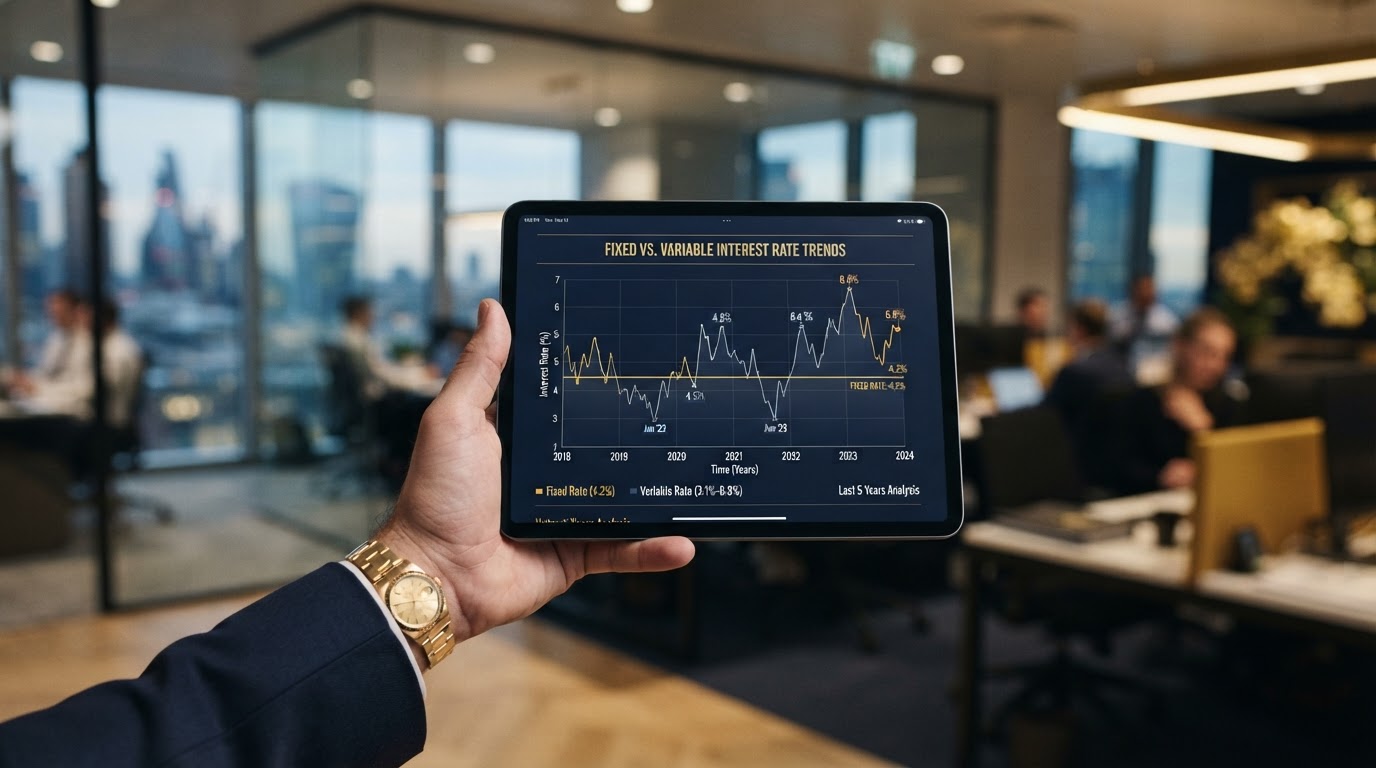
A fixed rate locks your payment for the full term, typically five years. You know exactly what you'll pay every month, regardless of what the Bank of Canada does. That certainty has real value — especially when your budget has little room for surprises. The trade-off is that you pay a premium for that certainty: fixed rates are usually higher than variable at any given moment.
What a variable rate gives you
A variable rate moves with your lender's prime rate, which tracks the Bank of Canada's overnight rate. When rates fall, your payment drops (or more of it goes to principal); when they rise, your payment rises. Historically, variable rates have cost less over the long run — but 'historically' is not a guarantee, and the ride can be bumpy.
The question that actually matters
Forget the headlines for a moment. The real question is: could you absorb a 1%–2% rise in your payment without it hurting? If the answer is no — because your budget is tight or your income is variable — the certainty of fixed is worth the premium. If the answer is yes, variable's long-run edge may serve you. Rate is one factor; fit is the deciding one.
And the term matters too
Beyond fixed vs variable, the length of your term changes everything. A shorter term hedges against falling rates; a longer term locks in certainty. We model each against your cash flow and your plans — moving, renovating, a child starting school — so the choice fits your life, not just the market.
Want a personalized answer?
These articles are the starting point — not the end.
Talk to an advisor about your specific situation. The first conversation is free, no-obligation, and in plain language.
Book a Free Consultation