In a competitive market, the difference between the buyer who gets the house and the one who loses it often comes down to one document: a pre-approval letter. Yet most buyers treat it as an afterthought. Let's fix that.
What pre-approval actually gives you
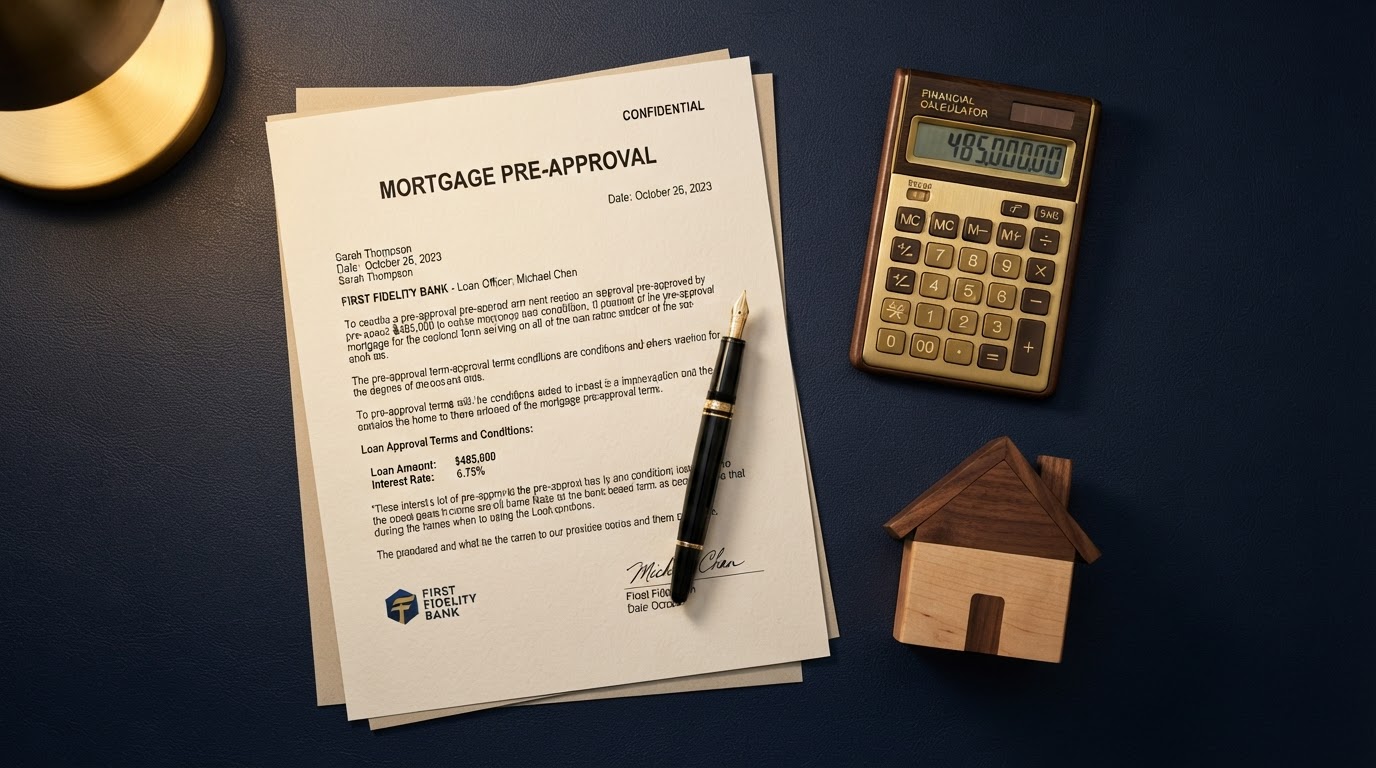
A pre-approval is a lender's conditional commitment to finance a purchase up to a set amount, at a set rate, for a set period — usually 90 to 120 days. It's not a guarantee of funding, but it's the strongest signal you can send to a seller short of cash.
- A firm purchase budget, grounded in real numbers.
- A rate hold that protects you if rates climb while you shop.
- Serious-buyer credibility that strengthens every offer you make.
What you'll need to gather
Lenders want to see a complete financial picture. Have it ready before you apply and the process moves fast. Missing documentation is the number-one reason pre-approvals stall.
- Two years of T1 general filings and Notices of Assessment.
- Recent pay stubs and an employment letter.
- Proof of down payment — savings statements, gift letters, or RRSP/FHSA balances.
- A list of current debts and monthly obligations.
What pre-approval doesn't do
It doesn't guarantee final approval — that comes after the lender reviews the specific property. It doesn't lock your amortization or final terms. And it doesn't replace a conversation about what payment actually fits your life, not just what you qualify for on paper.
Get pre-approved the smart way
A good pre-approval isn't just a rate quote — it's a budget conversation. We help you understand the difference between what you can borrow and what you'll be comfortable paying, so you shop with both confidence and margin. Start before the listings, not after them.
Want a personalized answer?
These articles are the starting point — not the end.
Talk to an advisor about your specific situation. The first conversation is free, no-obligation, and in plain language.
Book a Free Consultation