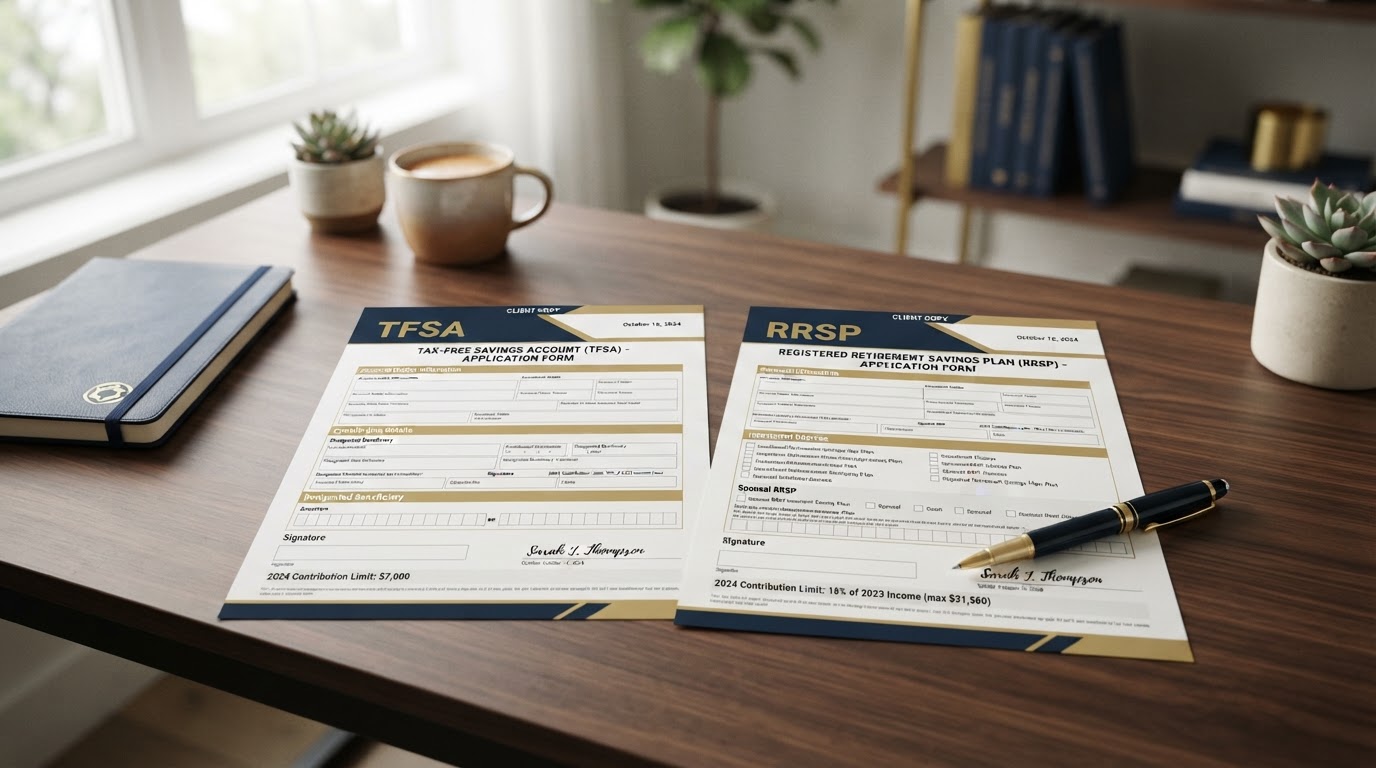
The TFSA and the RRSP are the two best savings vehicles available to Canadians — and the source of endless confusion about which to use first. The answer isn't one-size-fits-all. It depends on your income today, your income in retirement, and what you're saving for. Here's how to think about it clearly.
What the RRSP does
An RRSP gives you a tax deduction today — your contribution reduces your taxable income now — and your money grows tax-deferred until withdrawal, ideally in retirement when your income (and tax rate) are lower. The math favors the RRSP most when you're in a high bracket now and expect to be in a lower one later. It's a tool for tax-rate arbitrage as much as for saving.
What the TFSA does
A TFSA offers no upfront deduction, but every dollar of growth and every withdrawal is completely tax-free — forever. You contribute after-tax money, and you never pay tax on the gains. For most people, especially those in lower tax brackets now or who expect higher income later, the TFSA is the more flexible and often the better first stop.
So which comes first?
A useful framework, not a rigid rule: contribute to the RRSP when you're in a high marginal bracket and expect a lower one in retirement; otherwise, prioritize the TFSA. The practical version most clients end up with:
- Build a starter emergency fund first — in a TFSA savings account.
- Maximize the TFSA if your current tax bracket is low or moderate.
- Contribute to the RRSP when your income pushes you into a higher bracket.
- Use the RRSP refund to fund the next year's TFSA — a powerful combo.
The right order for you
There's no universal answer because the right order depends on your income trajectory, your timeline, and your goals. We help clients map their contribution room, their current and expected tax brackets, and their savings goals into a sequence that minimizes lifetime tax and maximizes growth. Both accounts are excellent; the sequence is what makes them work together.
Want a personalized answer?
These articles are the starting point — not the end.
Talk to an advisor about your specific situation. The first conversation is free, no-obligation, and in plain language.
Book a Free Consultation