The old rule of thumb — seven to ten times your income — gets repeated in every life insurance article, and it gets the answer wrong for almost everyone. The right amount of life insurance isn't a multiple of your salary. It's the answer to a more specific question: what would your family actually need if your income stopped tomorrow?
The needs-based calculation
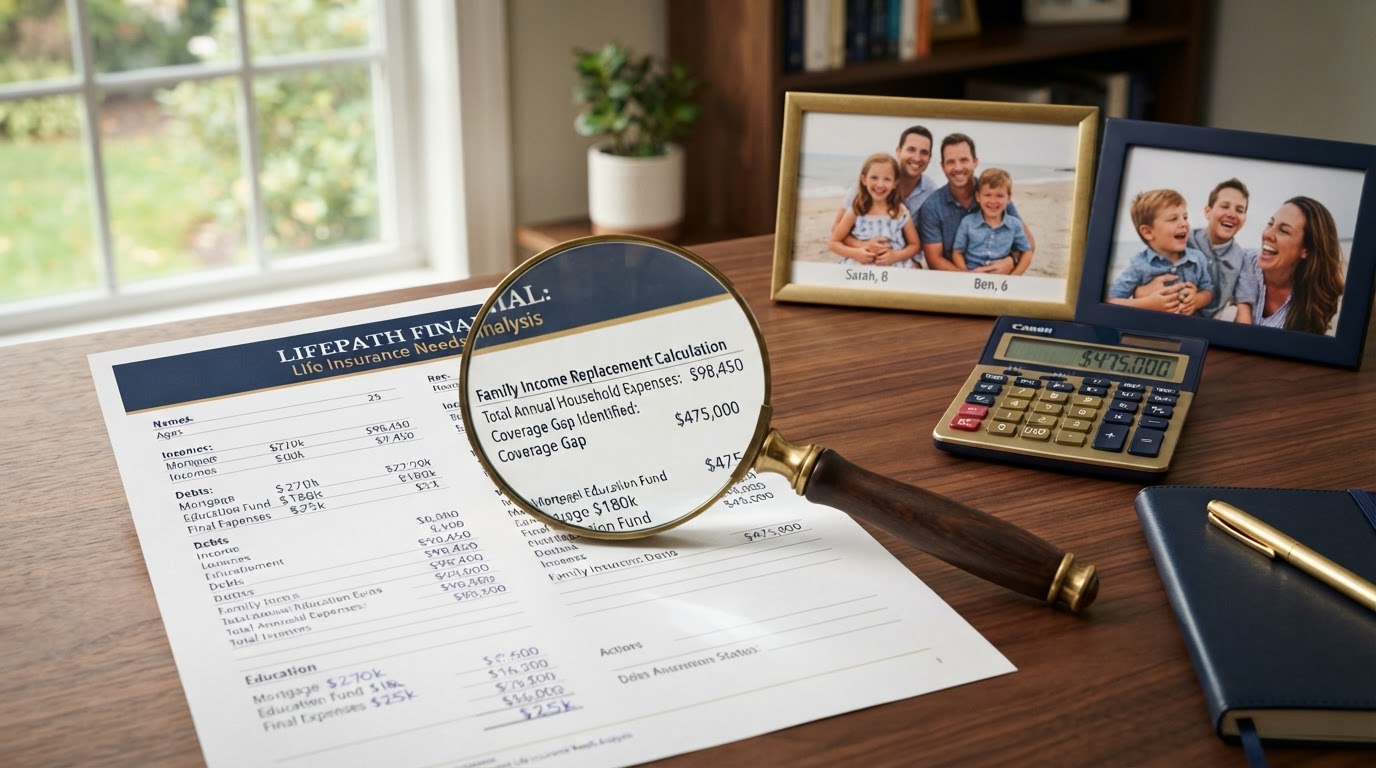
A proper calculation starts with the gap your death would create and works backward. It's more accurate than any rule of thumb — and not much harder to do.
- Income replacement: how many years of your income would your family need, at what standard of living?
- Debt payoff: mortgage, lines of credit, and any other obligations you don't want to leave behind.
- Future goals: children's education, a spouse's retirement, planned major expenses.
- Final expenses: funeral, legal, and estate settlement costs.
Then subtract what you already have
Your existing coverage matters. Employer group life, personal policies already in force, RRSP/TFSA balances, and other liquid assets all reduce the gap. The number you need is the difference — not the gross. Many families discover they're underinsured; some discover they're overinsured and paying for coverage they no longer need.
And factor in your stage of life
A family with young kids, a new mortgage, and one income needs more coverage than an empty-nester whose mortgage is paid off. Your needs change as life changes — which is why the right amount at 30 may be too much at 55. We revisit the calculation at every major milestone: a new home, a new child, a career change, and especially as the mortgage shrinks.
The right number, not a number
The goal isn't maximum coverage — it's right-sized coverage. Enough to protect your family without paying for protection you'll never use, structured to shrink as your needs shrink. We walk every client through a real needs analysis, grounded in their actual numbers, so the amount on the policy matches the reality of their life. That's how insurance earns its place in a financial plan.
Want a personalized answer?
These articles are the starting point — not the end.
Talk to an advisor about your specific situation. The first conversation is free, no-obligation, and in plain language.
Book a Free Consultation