Group disability coverage through an employer is a real benefit — and for many Canadians, the only disability protection they have. But it has structural limitations that matter most at the moment you need it. Understanding the gap between group and individual coverage is the difference between assuming you're protected and actually being protected.
Where group coverage falls short
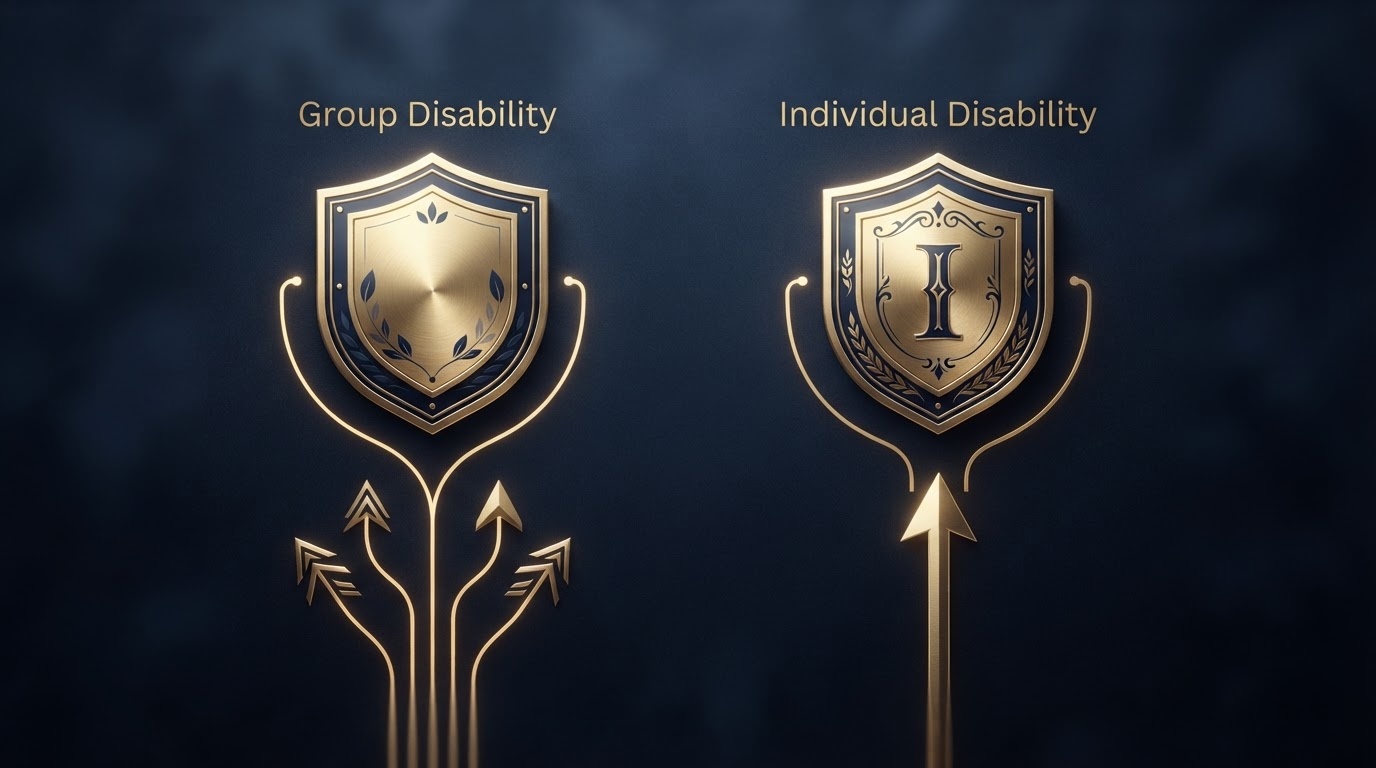
Group disability typically replaces 60%–70% of income, is taxable if the employer pays the premium, uses a restrictive 'any occupation' definition after a period, caps the benefit amount, and — critically — ends the day you leave the job. A serious illness that coincides with a job loss can leave you with no coverage at all at the worst possible moment.
What individual coverage adds
An individual policy you own is portable — it follows you between jobs — and can be structured with an 'own occupation' definition that pays if you can't do your specific work, with benefits paid tax-free. It can also top up a group plan to close the gap group caps and taxation create. For professionals and specialists, the definition alone is often worth the premium.
The right answer is often both
Group coverage is a valuable foundation; individual coverage fills its gaps. We map a client's group plan — benefit, definition, cap, tax treatment — and layer individual coverage to cover the shortfalls, so the protection holds whether they stay, leave, or face the very illness that makes work impossible.
Want a personalized answer?
These articles are the starting point — not the end.
Talk to an advisor about your specific situation. The first conversation is free, no-obligation, and in plain language.
Book a Free Consultation